Pay Day
1885 · Pay Day · Work 391 of 1,871
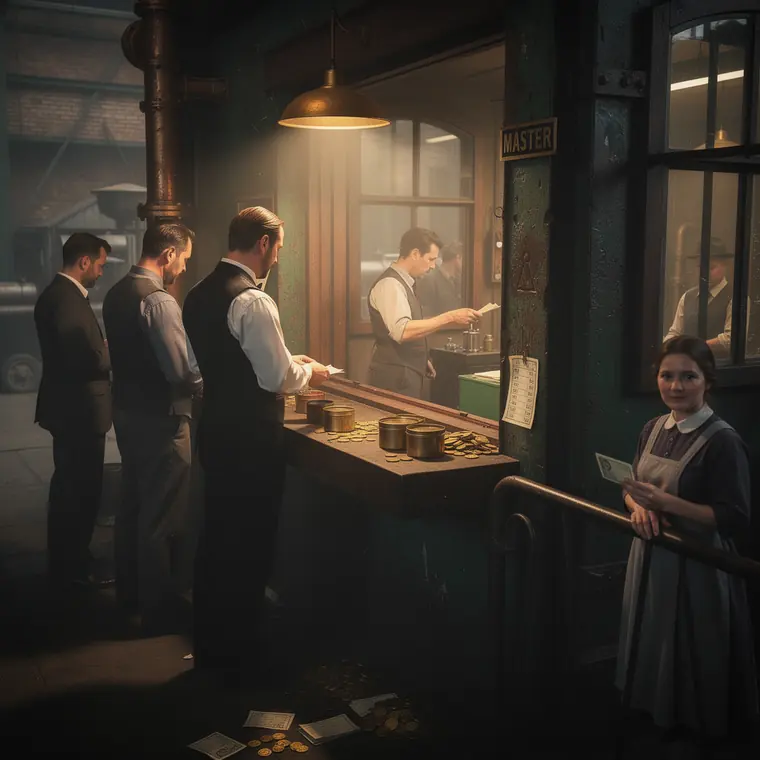
Workers queueing at a paymaster window in the works yard, coins counted into tin checks and paper packets on the ledge, a wife waiting at the gate rail.
- What it was used for
- Pay day and its deductions. The Truck Act of 1831 (1 & 2 Will. 4, c. 37, royal assent 15 October 1831) required that wages be made payable, and actually paid, in the current coin of this realm only, and declared payment in goods null and void. Penalties ran to £10 for a first offence, £20 for a second and up to £100 for a third. At the collieries payment was fortnightly: Guy Solomon shows for Townley Colliery the fortnightly cycle with its "pay Saturday", not commonly worked, and that between 1852 and 1856 the pit stood idle on the first Monday in 24 of 128 pay periods. What came off is in the Wylam Colliery paybills: fire coal, candles, powder, the fee for sharpening picks, and the contribution to the surgeon, constant throughout the period at sixpence per fortnight. Fines do not appear there as a separate item at all — they had already been worked into the wage.
- What was new
- What was new in 1831 was not the ban on truck but the consolidation: on the account of Lord Harris of High Cross, who moved repeal in the Lords in 1983, the Act replaced no fewer than 19 statutes by a wide prohibition, while applying to a dozen specified trades and excluding agriculture and domestic service. In 1887 it was extended to all manual workers within the meaning of the Act of 1875, and section 6 forbade an employer to impose terms as to the place at which or the person with whom a workman's wages were to be spent. The barb is in the statute itself: section 23 of the 1831 Act expressly excepted deductions for medicine and medical attendance, fuel, tools, rent of a company tenement, and for victuals dressed under the employer's roof and there consumed, provided the workman had signed a written agreement — and section 5 of the 1887 Act expressly left that exception standing. Only the Truck Act of 14 August 1896 then regulated deductions for fines and damaged goods.
Further reading
- William Bowstead, Law relating to Factories and Workshops, as amended and consolidated by the Factory and Workshop Act, 1901 (Sweet and Maxwell 1901), Appendix B: The Truck Acts, 1831 to 1896, mit Datum der königlichen Zustimmung
- Hansard, House of Commons, 9 November 1888: The Truck Acts — Deduction of Wages
- Hansard, House of Lords, 30 March 1983: Truck Acts (Repeal) Bill
- Guy Solomon, Work and earning in the nineteenth century: Townley Colliery as a case study, Continuity and Change 37 (2023)
- Guy Samuel Solomon, The living standards of Tyneside coal miners, 1836-1862 (MSc by Research, University of York 2014)